China’s August industrial profit data due to be published, markets brace for signs on growth and property drag
Beijing is set to publish monthly industrial profit figures on September 28, 2026. Economists and investors will treat the release as a near‑term barometer of manufacturing momentum, corporate margins and the extent to which China’s struggling property sector is weighing on firms.
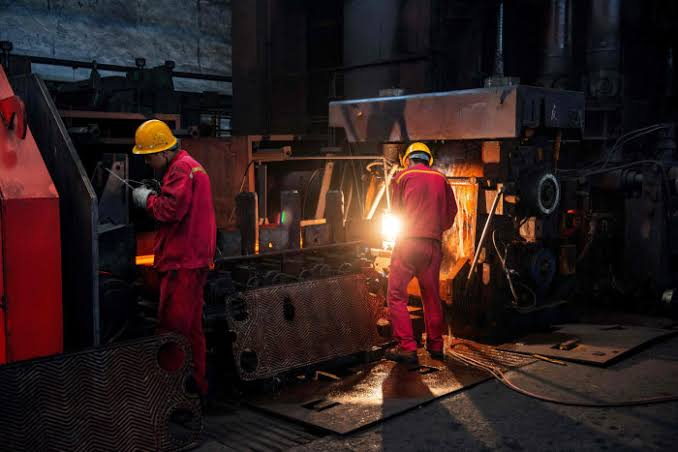
Beijing will publish official monthly industrial profit data for August on September 28, 2026, a routine statistical release that financial markets and economists view as an early indicator of the health of Chinese manufacturing and corporate margins. The report comes as policymakers step up targeted support for construction and infrastructure, while household demand and property investment remain sources of strain for many firms. Analysts say the August profit and related industrial indicators will be watched for three reasons. First, they provide an immediate read on factory profitability as commodity prices and producer selling prices move. Second, the numbers will shed light on the earnings impact of weaker property investment and slower home sales in many cities. Third, the series offers an early signal on whether recent policy measures, including faster approvals for project financing and liquidity injections ahead of the Golden Week holiday, are feeding through to corporate balance sheets. Why this release matters Chinas industrial profit series covers firms above a revenue threshold and is a timely snapshot of whether the manufacturing rebound seen earlier in 2026 is holding. A stronger than expected result would support the case that stimulus and credit support targeted at infrastructure and strategic industries have begun to raise industrial demand and margins. A softer print would underscore persisting demand weaknesses, reinforce worries about the property sectors drag on supply chains, and could complicate Beijings near term growth calculus. Policy backdrop Over recent weeks, Chinese authorities have signaled increased willingness to use financial tools and project financing to stabilise activity. The central bank has publicly committed to short term liquidity operations around the Golden Week holiday to ensure stable funding conditions for banks and markets. Meanwhile ministries and provincial authorities have accelerated approvals and funding for selected infrastructure and manufacturing projects, part of a broader push to boost high quality investment and underpin jobs. Markets and corporates Investors typically react to the industrial profit release in combination with other monthly macro indicators, such as industrial production, fixed asset investment and retail sales. If profits show a notable pickup, equity markets could receive relief because corporate earnings expectations would be easier to justify. Conversely, a pronounced decline in profit growth would likely deepen concern among foreign and domestic investors about the pace of demand recovery and the credit risks facing suppliers to the property sector. For many listed manufacturers, property developers and commodity suppliers, the report can materially alter near term revenue and funding plans. Companies exposed to construction materials, heavy machinery and industrial components are particularly sensitive to swings in construction activity. Banks and nonbank lenders that provide credit to developers and local infrastructure vehicles also monitor the data for signs of widening losses and higher provisioning needs. What analysts will look for Economists will parse the headline year on year change in industrial profits, but they will also look at sectoral splits, month on month seasonally adjusted trends, and the cumulative January to August outturn. Key areas of interest will include manufacturing categories linked to property, such as steel and building materials, and export oriented segments that could be benefiting from weaker domestic demand but still supported by external orders. Policy implications A mixed or weak print would raise pressure on Beijing to widen support measures beyond project funding and short term liquidity, possibly by stepping up tax and fee relief, accelerating approvals for local government special bonds, or loosening conditions on policy bank lending for construction and affordable housing. A stronger print would give authorities more room to calibrate interventions, focusing on credit quality and targeted support rather than broad based stimulus. Timing and next steps The National Bureau of Statistics release is scheduled for September 28, 2026. Market participants will immediately reassess growth forecasts, risk premiums and policy probabilities when the data appear. The industrial profit figures will be integrated with other monthly releases currently scheduled in late September and early October, including manufacturing purchasing managers indexes, to form a fuller near term view of Chinas economic trajectory. Why readers should care China remains the largest engine of global manufacturing, and signs of strengthening or weakening corporate profitability in China have implications for commodity prices, supply chains and multinational earnings. For investors and companies with exposure to China, the industrial profit data are a practical barometer of demand conditions and an input to timing and scale of capital allocation decisions.
Topics
LocationChina National Bureau of Statistics release